Chapter 1
Chapter 1
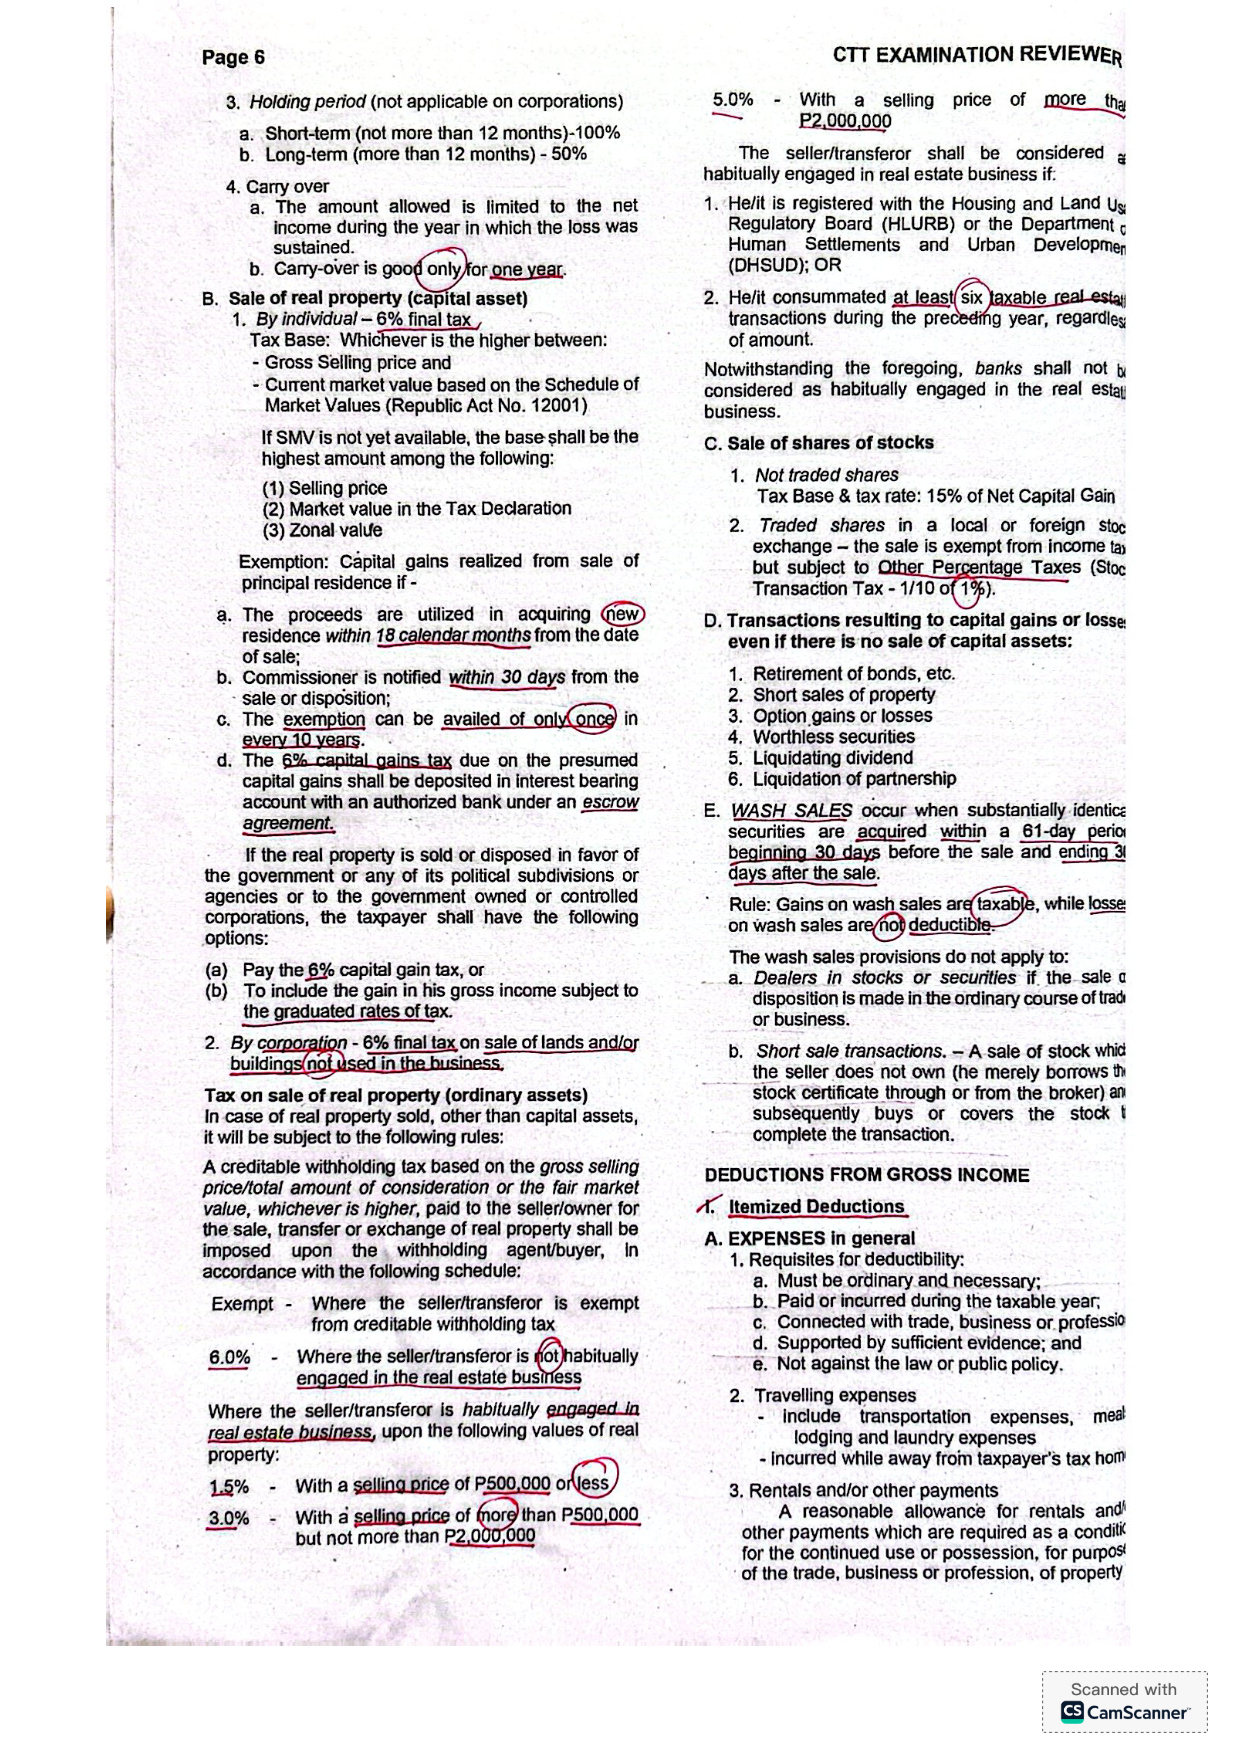
3. Holding period (not applicable on corporations)
a. Short-term (not more than 12 months)—100%. b. Long-term (more than 12 months)—50%.
4. Carry over
4. Carry over
income during the year in which the loss was sustained.
b. Carry-over is good only for one year.